Investing for Homemakers: Getting Started, One Step at a Time
Introduction
There is a particular kind of math that happens in a homemaker’s head every single day. Stretch this month’s grocery budget a little further. Set aside a fixed amount for the children’s school fees, months before they are due. Keep a small buffer for the unexpected. None of this is called “investing.” But look closely, and it already is.
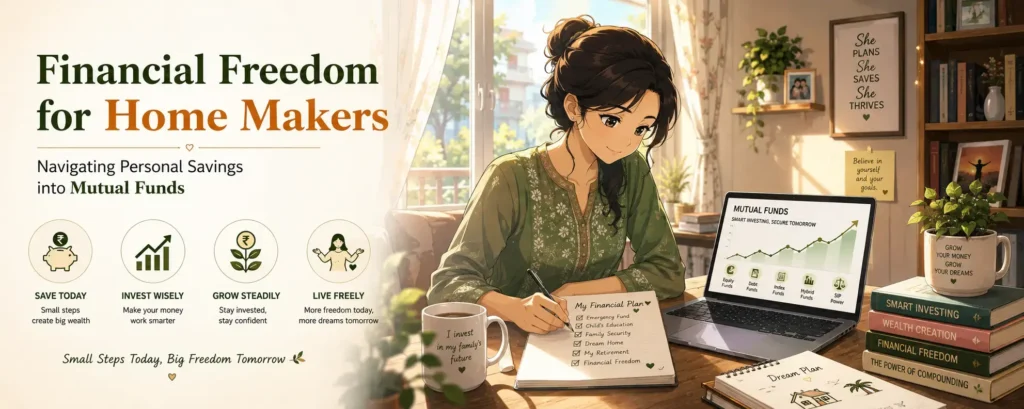
Investing for homemakers doesn’t have to mean learning an entirely new language from scratch. It’s closer to a familiar habit, pointed at a wider set of tools. From understanding SIP for homemakers to exploring other investment options, the first step is simply knowing how different choices work. This article is a gentle, plain-language look at the investment options for homemakers in India, how to start investing as a housewife in practice, and what that first step actually looks like.
From Household Budget to Investment: The Skills You Already Have
Before naming a single investment option, it’s worth saying something plainly: budgeting a household is a genuine financial skill. It involves forecasting, prioritising, delaying gratification for a bigger goal, and adjusting when circumstances change. These are the same instincts long-term investing asks for.
The gap, usually, isn’t skill. It’s exposure. Many households manage money almost entirely through savings accounts, fixed deposits, or gold, tools built for safety and liquidity, not necessarily for outpacing inflation over the long run. The shift from household budget to investment is smaller than it looks; it mostly means understanding the wider set of options available, so the same discipline can be pointed at long-term growth, not just short-term safety.
What Investing Means for Homemakers
Strip away the jargon, and investing is a simple idea: instead of letting money sit still, you put it to work so it can grow on its own over time.
That’s really the whole concept. A rupee kept in a jar stays a rupee, and slowly buys less as prices rise around it. A rupee that is invested, put into an instrument designed to grow, has the chance to become more than a rupee over time. Nothing about that requires special expertise. It requires understanding where the money is going, and giving it time.
There are many ways to do this in India, from familiar options like gold and fixed deposits to market-linked ones like mutual funds. Each works a little differently, but they all share this same underlying idea: money set aside with intention, given a chance to grow, rather than money simply held in reserve. When people search for the best investment options for saving money at home, what they’re often really asking is this same question: which of these tools turns idle savings into something working toward a goal. The specifics of any one option matter less at the start than understanding this basic shift in thinking, from saving what’s left over, to deliberately putting money to work.
How to Beat Inflation with Household Savings
Here’s a detail that often goes unnoticed: money sitting in a low-interest instrument is not standing still. It is slowly losing purchasing power to inflation, even while the number in the passbook stays the same or grows only slightly.
If prices rise by around 6% a year and a saved amount earns much less than that, the same amount buys a little less each year, quietly, without one dramatic moment to notice it. This isn’t a reason to abandon safe instruments, which remain useful for near-term needs and emergencies. It’s a reason to understand that “safe” and “growing faster than inflation” are two different jobs, and few single products do both well over the long run. This is exactly why many investors choose to hold a mix of instruments rather than relying on just one.
SIP for Homemakers: A Simple Starting Point
Among these options, many first-time investors find the Systematic Investment Plan, or SIP, an accessible way to begin, for a specific reason: it doesn’t require a large lump sum.
This is one of the common ways mutual funds for beginners in India are introduced, since it removes the need to save up a large amount before starting at all.
A SIP means contributing a fixed amount into a mutual fund at a regular interval, usually monthly, similar in rhythm to a gold savings scheme or a recurring deposit many households already use.
For SIP for homemakers, starting with an amount that fits comfortably within the household budget can help make investing a regular financial habit. Many fund houses allow SIPs starting from a few hundred rupees a month, making it possible to begin small and build the habit over time.
This is one starting point among several, not the only one. It’s worth being direct: mutual funds carry market-linked risk, and no mutual fund is risk-free. Returns are never guaranteed, and every fund’s specific risk profile is detailed in its scheme documents, which are worth reading before investing.
Financial Independence for Housewives: Investing in Your Own Name
One more distinction is worth naming clearly, regardless of which instrument is chosen: an investment held in a homemaker’s own name is different from household savings managed jointly or held in someone else’s name.
Holding an investment individually, whether it’s a fixed deposit, gold, or a mutual fund, builds something beyond the money itself: a personal financial record, a documented history, and independent decision-making experience. Among the benefits of having investments in one’s own name that women often mention is exactly this: it becomes its own quiet form of financial independence and confidence, separate from, but supportive of, the household’s overall finances.
This is general information about why individual financial identity can matter. It isn’t a recommendation on how any particular household should structure its finances or which instrument to hold it in. Those are personal decisions, shaped by each family’s own circumstances.
How to Start Investing as a Housewife: First Steps
Getting started, practically, tends to follow a similar sequence regardless of which instrument is chosen first.
Complete KYC. The KYC (Know Your Customer) process for non-working women in India is the same one-time process required of any resident individual: generally a PAN card, Aadhaar, and basic address verification, mostly completable online, with no income proof required to begin.
Start with what you understand. Whether that’s a recurring deposit, a small gold scheme, or a modest SIP, starting with an instrument whose mechanics feel clear tends to build confidence for exploring others later.
Read before you commit. Every formal investment product, from a fixed deposit’s terms to a mutual fund’s scheme documents, spells out its features, costs, and risks. Reading these, or discussing them with a distributor or advisor, is worth the time before committing money.
Build gradually. Getting started doesn’t require choosing the “perfect” mix on day one. Many investors begin with one familiar instrument and add others as their understanding grows.
This is general information about the mechanics of getting started, not a recommendation of any particular product, amount, or sequence, which is best based on individual research and, where useful, a conversation with a qualified advisor.
How Dhanvantri Capital Services Pvt. Ltd. Can Help with Investing for Homemakers
Dhanvantri Capital Services Private Limited is an AMFI-registered Mutual Fund Distributor (MFD), ARN-194216. Our focus is specifically on mutual funds and SIF strategies, one part of the broader investment landscape described above.
For investors exploring investing for homemakers, our role as an MFD includes:
- Investor education: explaining how mutual funds and SIPs work, in plain, accessible language, as one option within a wider set of choices.
- Process support: helping investors understand KYC requirements and the practical steps to begin investing in mutual funds.
- Disclosure support: helping investors locate and understand scheme documents before investing.
- Ongoing support: remaining available as questions come up along the way.
We do not provide investment advice or financial planning services. Any decision to invest, including the choice of instrument, fund, or amount, should be based on the investor’s own reading of relevant documents and independent judgment, consulted with a qualified advisor where appropriate.
A Concluding Thought on Investing for Homemakers
The instincts behind running a household, patience, planning, protecting what matters, are not separate from the instincts behind investing. They are the same instincts, simply pointed at a wider set of tools. Understanding what those tools are, and how each one works, is often the only real distance between managing a household and building something that grows alongside it.
Important Disclosure: Dhanvantri Capital Services Private Limited is an AMFI Registered Mutual Fund and SIF Distributor (ARN-194216). Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. Past performance may or may not be sustained in the future and should not be construed as an indicator of future returns.
Table of Contents
Frequently Asked Questions
Yes. Any resident Indian individual, including a homemaker without independent income, can invest in mutual funds after completing KYC, using funds from personal savings, gifts, or household allocations, subject to normal tax and regulatory rules.
Most fund houses allow a SIP to be set up with an amount as low as a few hundred rupees a month, linked to a bank account through auto-debit, so no large lump sum is needed to begin.
It’s the same one-time process required of any resident individual: generally a PAN card, Aadhaar, and basic address verification, mostly completable online, with no income proof or employment status required.
This depends on individual goals, but common options range from familiar, low-risk instruments like recurring deposits and gold to market-linked ones like mutual funds, each suited to a different purpose, from short-term safety to long-term growth.
Money kept in low-interest instruments loses purchasing power over time as prices rise. Instruments designed for growth, such as mutual funds, aim to outpace inflation over the long term, though this comes with market-linked risk rather than a fixed, guaranteed return.
Investments in an individual’s own name build a separate financial record, history, and independent decision-making experience, which many describe as a quiet form of financial security and confidence, alongside the household’s overall finances.
Leave a Reply