Dhanvantree

Dhanvantree

Dhanvantree

ITR Filing AY 2026-27: Deadlines, Section 87A Rebate, and Every Rule You Need to Know

hero image of dhanvantree ITR Filing AY 2026-27 Deadlines, Section 87A Rebate, and Every Rule You Need to Know blog

Introduction

Missing your ITR filing deadline by even a day can cost you the right to carry forward losses. Earn ₹1 more than a key threshold, and a ₹60,000 tax rebate disappears entirely. Income Tax Return filing isn’t just paperwork, it’s a system of thresholds, defaults, and deadlines that quietly work for you or against you, depending on whether you understand them.

This article covers everything you need for Assessment Year 2026-27 (Financial Year 2025-26) exact deadlines by taxpayer category, how the Section 87A rebate can bring your tax bill to zero, the New Tax Regime default rules, common filing mistakes, and a pre-filing checklist you can run through before you submit.

What Is the ITR Filing Last Date for AY 2026-27?

For most individual taxpayers, the ITR filing last date is 31 July 2026. Businesses and professionals not requiring an audit get until 31 August 2026, audit cases have until 31 October 2026, and belated returns can be filed up to 31 December 2026 though with real trade-offs, explained below.

ITR Filing Due Dates for AY 2026-27 (Full Table)

Your deadline depends on your taxpayer category and the ITR form you file, not a single universal date.

For the first time, non-audit business and professional taxpayers filing ITR-3 or ITR-4 get a full extra month beyond the salaried deadline, a meaningful change if that’s your category.

The Real Cost of Filing a Belated Return

Filing late isn’t just about a penalty fee. It comes with two consequences that are easy to overlook:

  • You lose the right to carry forward capital or business losses to future assessment years.


  • You’re automatically locked into the New Tax Regime with no option to switch to the Old Regime, even if it would have reduced your tax bill.

If either of those applies to you, treat July or August not December as your real deadline.

A Quiet Legal Shift Behind This Year's Filing

This filing season sits at a transition point. The new Income Tax Act, 2025 came into force on 1 April 2026  but since AY 2026-27 covers income earned before that date (FY 2025-26), your return this year is still governed entirely by the older Income Tax Act, 1961. Nothing about how you calculate or file has changed yet. That shift only applies from Tax Year 2026-27 onward, with returns due in 2027.

New Tax Regime vs Old Tax Regime: Understanding the Default

Here’s something many taxpayers still get wrong: if you file without actively choosing otherwise, you’re taxed under the New Tax Regime by default. HRA, Section 80C, Section 80D  none of the traditional deductions apply unless you actively opt out.

  • If you’re salaried with no business income: you can switch between the Old and New Regime every single year, directly within your ITR, as long as you file by the due date.

  • If you have business or professional income: that flexibility disappears. To use the Old Regime, you must file Form 10-IEA on the e-filing portal before your due date. And once you switch back to the New Regime, you can only do it once in your lifetime.

Section 87A Rebate Explained: How to Pay Zero Income Tax on Your ITR Filing

Before the numbers, one distinction matters: a deduction reduces your taxable income before tax is calculated. A rebate wipes out the tax you’ve already calculated. Section 87A is a rebate and used correctly, it can bring your final tax liability to zero.

Section 87A Rebate Limits for FY 2025-26 (AY 2026-27)

Financial circumstances and goals can evolve. Periodic reviews help investors assess whether their mutual fund holdings continue to align with their objectives and requirements.

Tax Regime

Income Limit

Maximum Rebate

Old Regime

₹5,00,000

₹12,500

New Regime

₹12,00,000

₹60,000

Why Salaried Employees Can Earn Up to ₹12.75 Lakh Tax-Free

The New Regime’s Standard Deduction of ₹75,000 stacks directly with the Section 87A rebate. Run the math, and a salaried employee earning up to ₹12,75,000 gross can end up paying zero income tax: the ₹75,000 deduction brings net taxable income down to exactly ₹12,00,000, and the ₹60,000 rebate erases the tax on that amount entirely.

The ₹1 Cliff and How Marginal Relief Protects You

Think of the tax rebate as a steep cliff rather than a gentle slope. If you earn exactly ₹12,00,000, you get a full ₹60,000 tax rebate (meaning you pay zero tax). But if you earn just ₹1 more (₹12,00,001), that entire ₹60,000 discount vanishes instantly, not just the tax on that extra ₹1.

Without a safety net, this rule would actually punish you for making more money, leaving you with less take-home pay than someone who earns less than you.

To fix this unfair jump, the government uses a rule called Marginal Relief. It acts as a shield, making sure that your extra tax is never higher than the extra income that pushed you over the ₹12 lakh limit.

Who Cannot Claim the Section 87A Rebate

The Section 87A rebate is available only to resident individuals. It cannot be claimed by non-residents, companies, partnership firms, or Hindu Undivided Families (HUFs).

The rebate also does not apply to certain types of income that are taxed at special rates. For example:

  • Short-Term Capital Gains (STCG) under Section 111A, which are taxed at 20%.

  • Long-Term Capital Gains (LTCG) on listed equities are tax-free up to ₹1.25 lakh per financial year under Section 112A. Any profit above this limit is taxed at a flat rate of 12.5%. 

This means that even if your total income is within the rebate limit, you may still have to pay tax on these types of capital gains.

What's New in the ITR Forms for AY 2026-27

A few form-level changes are worth confirming before you start filing, since using the wrong form can get your return flagged as defective:

  • ITR-1 now covers up to two house properties, not just one a genuine simplification for salaried filers with a second home. A third property still requires ITR-2.
  • Company directors must file ITR-2 or ITR-3, ITR-1 isn’t an option for them.
  • Agricultural income over ₹5,000 also pushes you out of ITR-1.
  • Schedule AL (Assets & Liabilities) disclosure is now only mandatory above ₹1 crore total income, a relief for taxpayers who previously had to itemize assets at a lower threshold.
  • ITR-2 now includes a separate field for reporting buyback-related capital losses, helping taxpayers disclose these transactions correctly under the revised tax rules. 

Common ITR Filing Mistakes to Avoid

1. Missing Income the Tax Department Already Knows About

Savings account interest, fixed deposit interest, dividends, rental income, and capital gains are the most frequently overlooked income sources and they are not actually hidden. The Income Tax Department tracks all of this through your Annual Information Statement (AIS) and Form 26AS. Miss even a small interest payout, and an automated mismatch notice under Section 143(1) is often just a matter of time.

2. Trusting Pre-Filled Data Without Checking It

The e-filing portal now pre-fills more of your return than ever, pulling data from the AIS, stock depositories, and banking institutions. While convenient, this system is not infallible. Duplicate entries or incorrect transaction classifications can happen. Always cross-check pre-filled values against your personal bank statements, capital gains reports, and tax credit certificates before clicking submit.

3. Waiting Too Long When Form 16 Is Delayed

Don’t let a slow employer turn into a rushed, last-minute filing. If your Form 16 is delayed:

  • Download your AIS and Form 26AS from the e-filing portal to verify your recorded Tax Deducted at Source (TDS).
  • Reconcile your monthly payslips against actual bank credits to accurately reconstruct your gross salary.
  • Gather your investment and deduction proofs early, especially if you are planning to opt out of the default regime.
  • If numbers still do not match, use the portal’s feedback system to dispute incorrect AIS entries before submitting.

4. Failing to Disclose All Active Bank Accounts

Many taxpayers mistakenly believe they only need to report the primary bank account where they receive their salary or business income. By law, you must disclose every single active bank account held in India in your name at any time during the financial year (excluding truly dormant accounts that have been inactive for over two years). Crucially, ensure that at least one primary account is pre-validated on the portal, or your tax refund cannot be electronically credited.

5. Blindly Copying "Book Profits" for Business Returns (ITR-3 & ITR-4)

If you have business or professional income, a frequent mistake is assuming that your standard accounting profits match your taxable profits. For tax purposes, you must reconcile your books with the Income Computation and Disclosure Standards (ICDS). Differences in how ICDS mandates inventory valuation, revenue recognition, or depreciation mean that your business ledger profits must almost always be adjusted before they are entered into your ITR.

6. Choosing the Wrong Tax Form

Using the wrong ITR form can cause your return to be flagged as defective under Section 139(9). For instance, while ITR-1 is the default for salaried individuals, you are legally barred from using it if you own more than two house properties, have agricultural income exceeding ₹5,000, hold unlisted equity shares, or serve as a director in a company. Take a moment to verify your specific income streams against the criteria for ITR-1, ITR-2, or ITR-3 before initiating the form utility.

ITR Pre-Filing Checklist

Run through this before you hit submit:

  • Compared Old vs. New Regime outcomes using current Standard Deduction figures (₹75,000 vs ₹50,000)
  • Filed Form 10-IEA before the due date, if opting for the Old Regime with business/professional income
  • Confirmed you’re using the correct ITR form for your income sources
  • Cross-checked pre-filled data against your own AIS, Form 26AS, and personal records
  • Separated special-rate capital gains (Sections 111A, 112A) to confirm the 87A rebate is calculated correctly
  • Filing before your July/August deadline, if carrying forward losses matters to you
  • Pre-validated your refund bank account on the e-filing portal

Why Filing Your ITR On Time Pays Off (Even If You Earn Below the Tax Slab)

If your income is below the tax slab, you might think you don’t need to file an Income Tax Return (ITR). However, filing a “Nil ITR” (a return showing zero tax owed) on time acts as a powerful financial tool.

Here is how a clean, timely filing history helps you in the long run:

1. Your Losses Become an Asset, Not a Dead End

If you lose money in business or the stock market, those losses don’t have to vanish into thin air. If you file your ITR on time, the government allows you to carry forward these losses for future years. This means when you make a profit next year, you can subtract this year’s losses from it, drastically lowering your future tax bill. If you file late, you lose this privilege entirely.

2. Loans Move Much Faster

When you apply for a home, auto, or business loan, banks look at your financial discipline. Lenders typically expect to see 2 to 3 years of consistent, clean ITR history to verify your income stability. If you haven’t been filing because you were under the tax slab, the bank has no official paperwork to trust, which can delay or completely stall your loan approval.

3. It's Your Only Route to Get a Refund

Sometimes, a client or an employer might deduct Tax Deducted at Source (TDS) from your payouts, or you might have overpaid advance tax. If your total income for the year ends up being under the tax slab, that deducted money actually belongs to you. However, the government won’t just send it back automatically; the only way to get your refund is by filing an ITR.

4. Visa Officers Pay Attention

When you apply for a visa to travel or study abroad, embassies want proof that you have deep roots and financial stability in India. A steady, consecutive history of filing your ITR even if it shows a low income is read by visa officers as official evidence that you are a law-abiding, financially trackable citizen.

5. It Builds Your Business Credibility

A consistent filing history serves as an informal certificate of credibility in the professional world. If you ever want to apply for government tenders, enter corporate partnerships, or sign commercial property leases, a clean track record of timely ITR filings proves that your background is stable and transparent.

Conclusion

Income Tax Return filing is more than an annual compliance requirement; it is an important part of maintaining a healthy financial record. Understanding the applicable deadlines, choosing the appropriate tax regime, verifying information before filing, and staying updated with changes in tax regulations can help taxpayers avoid unnecessary complications and complete the filing process with greater confidence.

Dhanvantri Capital Services Pvt. Ltd. is an AMFI-registered Mutual Fund Distributor (ARN-194216) believes that improving financial awareness is an essential step toward better financial decision-making. Through educational articles, investor awareness initiatives, and simplified explanations of important financial and regulatory developments, we aim to make complex financial topics easier to understand for investors.

Whether you’re filing your first Income Tax Return or reviewing the latest changes for AY 2026–27, staying informed and referring to reliable sources can make the process smoother and more efficient. As tax laws and regulations continue to evolve, readers are encouraged to verify the latest information on the official Income Tax e-Filing portal and consult a qualified Chartered Accountant or tax professional whenever required.

Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing. This article is intended solely for educational and informational purposes and should not be construed as investment advice, financial advice, legal advice, or a recommendation to invest in any product or strategy.

Table of Contents

Frequently Asked Questions

What is the ITR filing last date for AY 2026-27?

31 July 2026 for salaried individuals and pensioners; 31 August 2026 for freelancers and professionals without audit requirements; 31 October 2026 for audit cases.

Yes, as a belated return, up to 31 December 2026 — but you’ll lose the ability to carry forward certain losses and won’t be able to switch to the Old Regime if you have business or professional income.

₹60,000 under the New Regime for taxable income up to ₹12,00,000, and ₹12,500 under the Old Regime for taxable income up to ₹5,00,000.

If you have business or professional income and want the Old Regime, yes it must be filed before your due date each year you want to opt out of the New Regime default.

No. It doesn’t apply to income taxed at special rates, including Short-Term Capital Gains under Section 111A or Long-Term Capital Gains under Section 112A.
Ready to make your first investment? Get in touch.

Mutual Fund Distributor vs Finfluencer: Understanding Their Role in Financial Awareness in India

Hero image of dhanvantree blog on Mutual Fund Distributor VS Finfluencer

Introduction

Financial awareness in India continues to grow as more individuals explore investing, personal finance, and wealth-building concepts. According to SEBI’s Investor Survey 2025, awareness of financial products has increased significantly, yet actual participation in securities markets remains relatively low. This gap between financial awareness and investment participation in India has sparked important conversations about how investors learn, evaluate opportunities, and make financial decisions. Two prominent contributors to this ecosystem are Mutual Fund Distributors (MFDs) and finfluencers.

While both play a role in improving financial literacy in India, their functions, responsibilities, and methods of engagement are different. Understanding the distinction between a mutual fund distributor vs finfluencer can help investors make more informed decisions.

How Finfluencers Contribute to Financial Literacy in India

The rise of digital platforms has transformed how people access financial information. Finfluencers use platforms such as YouTube, Instagram, LinkedIn, and X to discuss topics ranging from SIP investment in India and budgeting to taxation and market developments.

This form of personal finance education on social media in India has helped simplify complex concepts for a wider audience. Educational content covering SIPs, mutual funds, asset allocation, and investing basics has encouraged many first-time investors to begin learning about financial markets.

The growth of financial content online has also increased awareness among younger investors and audiences in tier-2 and tier-3 cities through regional-language content.

However, investors should remember that financial education and regulated financial services are not the same. Since the regulatory status of content creators may vary, information shared online should be evaluated carefully before acting on it.

Is Finfluencer Advice Safe for Investment Decisions?

This is one of the most common questions among new investors.

Finfluencer content can support investor education and awareness. However, investors should independently verify information and evaluate whether it aligns with their financial goals, investment horizon, and risk appetite before making decisions.

Understanding the Role of a Mutual Fund Distributor

An AMFI registered mutual fund distributor operates within the mutual fund distribution framework and facilitates access to mutual fund products for investors. The Mutual Fund Distributor is required to maintain valid registration credentials and comply with applicable regulations governing mutual fund distribution activities.

Many investors exploring goal-based financial investing often seek support in understanding mutual fund products, investment processes, and long-term investing concepts.

Some areas where MFDs may assist investors include:

Goal-Based Investing Considerations

Investors frequently evaluate mutual fund investments in the context of long-term goals such as retirement planning, children’s education, wealth creation, or major life milestones.

A Mutual Fund Distributor may help investors understand mutual fund products and evaluate options that align with their stated financial objectives.

SIP Discipline Through Market Volatility

A common challenge for investors is maintaining discipline during periods of market uncertainty.

When discussing SIP investment in India, investor behaviour during market volatility is often as important as the investment itself. Educational discussions around SIP discipline can help investors remain focused on long-term objectives.

Understanding Mutual Fund Holdings Over Time

Financial circumstances and goals can evolve. Periodic reviews help investors assess whether their mutual fund holdings continue to align with their objectives and requirements.

Why Financial Awareness and Investor Participation Are Different

One of the key findings from the SEBI Investor Survey 2025 is that awareness does not always translate into participation. Many investors understand basic financial concepts but may still hesitate to begin investing due to uncertainty, lack of confidence, information overload, or difficulty evaluating available options.

This is why discussions around financial awareness vs investment participation in India continue to receive attention from policymakers, financial institutions, educators, and market participants.

Both finfluencers and Mutual Fund Distributors contribute to this ecosystem in different ways. Finfluencers can increase awareness and curiosity, while Mutual Fund Distributors facilitate access to mutual fund products within a regulated framework.

How to Verify an AMFI Registered MFD

Investors looking to work with a Mutual Fund Distributor should verify registration credentials before proceeding. You can verify an AMFI registered mutual fund distributor by checking their ARN (AMFI Registration Number) through the official AMFI website.

Understanding these distinctions can help investors determine which type of financial professional may be appropriate for their requirements.

Conclusion

The conversation around mutual fund distributor vs finfluencer reflects the changing landscape of financial awareness in India.

Finfluencers have expanded access to financial education and made investing more approachable for many first-time learners. Mutual Fund Distributors continue to play an important role in facilitating access to mutual fund products and supporting investor participation.

As financial literacy in India continues to evolve, investors may benefit from combining credible financial education with careful evaluation of their own financial goals, risk appetite, and investment requirements.

Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing. This article is intended solely for educational and informational purposes and should not be construed as investment advice, financial advice, legal advice, or a recommendation to invest in any product or strategy.

Table of Contents

Frequently Asked Questions

Is the Section 87A rebate available on capital gains?

The key difference between a Mutual Fund Distributor vs Finfluencer lies in their primary role. A Mutual Fund Distributor facilitates access to mutual fund products and operates within the applicable mutual fund distribution framework. A finfluencer primarily creates educational or informational content related to personal finance and investing for a broader audience.

Finfluencer content can be useful for building financial awareness and understanding investment concepts. However, investors should carefully evaluate information shared online and conduct appropriate due diligence before making investment decisions. Financial content on social media may not always consider an individual’s financial goals, risk appetite, or investment horizon. Due to rising concerns over unregulated financial advice, investors are advised to keep track of official updates via the SEBI Regulations and Board Decisions Portal.

An AMFI registered mutual fund distributor may help investors understand mutual fund products, investment processes, SIPs, and long-term investing concepts. They can also facilitate mutual fund transactions and support investors throughout their investment journey.

Investors can verify an MFD’s credentials using the ARN (AMFI Registration Number) available through the official AMFI India Verification Tool. This is one of the most reliable ways to confirm the registration status of a Mutual Fund Distributor.

Goal-based investment refers to aligning investment decisions with specific financial objectives such as retirement planning, children’s education, home ownership, or other long-term goals. Investors frequently use this approach to structure their financial decisions around clearly defined objectives.

Recent studies, including market insights compiled in the SEBI Investor Survey Dashboard, have highlighted a gap between financial awareness and investment participation in India. Factors such as limited confidence, information overload, behavioural biases, and uncertainty about financial products may contribute to this gap.

Ready to make your first investment? Get in touch.

5 Practical Strategies to Manage FOMO Investing

Hero image of Dhanvantree blog on Beat FOMO with Strategy, Not Emotion

Introduction

Financial markets test your psychology just as much as your math. For retail investors, the biggest threat is rarely a market crash, it is FOMO investing, or the Fear of Missing Out.

When a sector or trending asset skyrockets, investors may sometimes allow emotions to override rational decision-making. Investors may sometimes enter after significant price appreciation, which can increase the risk of losses if market conditions subsequently reverse, and portfolios built on emotion rather than strategy.

Beating FOMO investing requires two things working in parallel: a disciplined emotional framework for investors, and strict regulatory guardrails enforced by Mutual Fund Distributors (MFDs). This guide covers both.

Why FOMO Investing Is the Biggest Threat to Retail Investors

Humans are wired to follow the herd. When everyone around you appears to be getting rich off a trending stock or sector fund, the evolutionary urge to join in is powerful and instinctive.

The problem is timing. By the time FOMO influences investment decisions, investors may sometimes enter after significant price appreciation has already occurred. Latecomers buy at the top, ride the crash downward, and often panic-sell at a loss locking in the very outcome they feared.

Herd mentality investing is not a character flaw. It is a cognitive bias that even experienced professionals struggle with. The solution is not willpower, it is building a system that makes emotional decisions structurally impossible.

Part 1: 5 Practical Strategies to Manage FOMO Investing

1. Write Your Own Investment Policy Statement (IPS)

Do not rely on willpower in the middle of a bull run, you will lose that battle every time.

Instead, write an Investment Policy Statement (IPS) during a period of market calm. Define your asset allocation clearly (for example: 70% equity, 30% debt). Set rules for which asset types qualify for your portfolio and which do not.

When the next hot trend emerges, you have a pre-written rulebook to consult. If a trending asset does not fit your documented strategy, you simply do not buy it – no debate required.

Why this works: Decision fatigue is eliminated before the emotional trigger arrives.

2. Automate Investing with a Systematic Investment Plan (SIP)

A Systematic Investment Plan (SIP) can be a useful tool that may help investors reduce emotionally driven investment decisions.

With a SIP, a fixed amount is automatically invested every month, regardless of market conditions. When prices are high, your fixed amount buys fewer units. When the market dips, it buys more. A SIP may help reduce the impact of trying to time the market.

SIPs also encourage disciplined investing by helping investors stay invested through different market cycles. Consistent investing may support long-term financial goals, subject to market risks and individual circumstances.

3. Consider Limiting Speculative Exposure

A smarter approach: Some investors choose to allocate a small portion of their portfolio to higher-risk opportunities, depending on their financial goals, risk appetite, and investment strategy.

The objective is to limit speculative exposure to an amount that even if the investment does not perform as expected the overall investment does not hamper from its goal.

4. Focus on Fundamentals, Not Price Charts

A vertical price chart going up is financial clickbait. It communicates momentum, but nothing about value.

Before investing in any asset, examine the fundamentals: earnings growth, price-to-earnings ratio, debt levels, and competitive moat. If you do not understand how a company generates revenue and creates value, you may wish to conduct additional research before investing.

The simple test: If the asset disappeared from headlines tomorrow, would you still want to own it? If the answer is no, FOMO is the only reason you are looking at it.

5. Mute the Financial Noise

Social media is a highlight reel. People post their 10x wins. They quietly delete the posts about their 80% losses.

Curating your information diet is a non-negotiable part of any retail investor psychology strategy. Unfollow accounts that promote daily ticker hype. long-term investing principles and disciplined wealth-building approaches.

What you consume shapes what you believe is normal. Protect that input aggressively.

Part 2: MFD Compliance Checklist — SEBI Regulations Every Distributor Must Follow

While investors manage their own behavioral finance, Mutual Fund Distributors (MFDs) carry a legal mandate to act as rational guardians, especially during periods of market euphoria, when clients are most vulnerable to FOMO-driven decisions.

SEBI regulations are not optional guidelines. They are enforceable obligations designed to protect retail investors from both market risk and distributor misconduct.

1. Robust KYC Verification & Risk Profiling

Mandatory KYC: Every client must have a fully verified KYC on file, including identity, residential address, and financial status before any transaction is executed.

Risk Profiling: Product discussions and investment facilitation should be aligned with the investor’s risk profile, financial objectives, and suitability considerations in accordance with applicable regulations.

2. Full Commission Transparency & Disclosure

MFDs are required to comply with disclosure requirements prescribed by SEBI, AMFI, and applicable regulations.

Recommending a fund because it offers a higher payout to the distributor, rather than because it suits the client – is a serious SEBI regulatory violation. Commission structure must never drive product selection.

3. Strict Marketing Standards & Performance Display

No guaranteed returns: Mutual Fund investments are subject to market risks. Promising or even implying fixed returns is strictly prohibited under SEBI regulations.

Standardized performance display: MFDs cannot cherry-pick a fund’s best six-month window to showcase performance. SEBI compliance mandates the display of returns across standardized time periods – 1 year, 3 years, 5 years, and since inception – benchmarked directly against the fund’s official index.

4. Operational Integrity & Client Data Security

No fund pooling: Investor money must flow directly from the investor to the Asset Management Company (AMC). It must never pass through or be held in a distributor’s bank account. This is an absolute prohibition with severe regulatory consequences.

Data security: Client information should be protected through appropriate security controls and handling practices in accordance with applicable laws, regulations, and organizational policies.

Conclusion

Successful long-term investing is a team effort between disciplined investors and compliant distributors.

When retail investors automate their habits through SIPs, follow a written IPS, and tune out financial noise — they eliminate the conditions that make FOMO investing so destructive. When MFDs rigorously uphold KYC, suitability, and commission transparency rules, clients are protected even when market euphoria peaks.

A disciplined and process-driven approach may help investors make more informed decisions over the long term, although investment outcomes are never guaranteed. Build your system around those three principles, and FOMO loses its power.

Statutory Disclaimer: Mutual Fund investments are subject to market risks. Please read all scheme-related documents carefully before investing.

Data Disclaimer: Data referenced in this article is based on publicly available sources including AMFI and third-party research platforms, and is for informational purposes only. This article is for informational purposes only and should not be construed as investment advice. Investors should evaluate suitability based on their financial goals, risk appetite, and consult a qualified financial professional before making investment decisions.

Note: Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The past performance of the schemes is neither an indicator nor a guarantee of future performance.

Table of Contents

Frequently Asked Questions

What is FOMO investing?

FOMO investing (Fear of Missing Out investing) refers to the tendency of retail investors to buy assets at market peaks because they fear being left behind during a rally. It is one of the primary causes of poor retail investor returns.

A Systematic Investment Plan (SIP) automates your monthly investment regardless of market conditions. This eliminates the emotional “when to buy” decision that drives most FOMO-related mistakes and encourages disciplined investing aligned with long-term financial goals

An Investment Policy Statement is a personal document that defines your asset allocation rules, investment goals, and risk tolerance. Writing it during calm market conditions prevents impulsive decisions during rallies.

MFDs are required to provide disclosures and communicate compensation-related information in accordance with applicable SEBI and AMFI regulations. They are also expected to follow KYC, risk-profiling, and other investor protection requirements as prescribed under the regulatory framework.

Goal-based investment refers to aligning investment decisions with specific financial objectives such as retirement planning, children’s education, home ownership, or other long-term goals. Investors frequently use this approach to structure their financial decisions around clearly defined objectives.

Ready to make your first investment? Get in touch.

Automate your SIP investment in India: Stop treating wealth like a part-time job

Automate Your SIP Investment in India — Stop Treating Wealth Like a Part-Time Job blog hero image

Introduction

In today’s economy, we’ve automated everything — our groceries, our entertainment, even our laundry. But when it comes to growing our money, most people revert to a manual, high-stress process. At Dhanvantri Capital Services, we call this the Automation Gap. Closing it with a disciplined SIP investment is the simplest way to transform your financial future.

Your Netflix runs on autopilot and your SIP investment can too. Discover how automating a Systematic Investment Plan (SIP) supports long-term financial discipline.

The invisible monthly tax: why your SIP investment keeps getting delayed

Every month, like clockwork, ₹399 leaves your account for a streaming service. You don’t “analyze” which movies they released that month. There’s no “waiting for a discount” on the subscription fee, and the monthly bank notification barely registers anymore.

We’ve all become experts at automated consumption. Set-and-forget systems govern our food delivery memberships, music apps, and even those gym memberships we treat more like a monthly donation because we rarely go.

“But when it comes to our future and our SIP investment? Suddenly, we feel the need to be active managers.”

We tell ourselves: “I’ll start my SIP when the market cools down.” “I’ll invest whatever is left after this long weekend trip.” “I’ll definitely look into a Systematic Investment Plan next month.” Sound familiar?

The Automation Gap: how flipping the SIP investment formula changes everything

Most individuals follow a deeply flawed financial formula and it silently sabotages every savings intention they have.

Flawed Mindset: Income − Expenses = Savings

Fixed Mindset: Income − Savings (Automated SIP) = Expenses

The problem with the flawed formula? Expenses are infinite, but your monthly income is finite. By the time the fun and the bills are paid, the amount left for your future is often negligible.

The practical shift is to treat your Systematic Investment Plan (SIP) like a priority monthly commitment, one that leaves your account on the 1st or 5th of every month before discretionary spending takes over your monthly cash flow. You aren’t “saving what is left.” You are “spending what is left” after securing your future. The shift is psychological, but the compounding impact is mathematical.

  • ₹32,087 Cr – SIP inflows in India, March 2026
  • ₹9.72 Cr – Active SIP accounts in India
  • ₹500/Monthly – Minimum SIP, less than most OTT plans

AMFI Monthly Data: India’s Association of Mutual Funds publishes official SIP inflow and folio statistics every month. March 2026 data confirms a record ₹32,087 crore in SIP contributions, with 9.72 crore contributing accounts.

Why manual investing fails and how automated SIP investment fixes it

Investing manually requires you to be a superhero every single month. You have to:

  1. Overcome inertia: You have to remember to log in and transfer the money.
  2. Battle the headlines: If the news says the market is “crashing,” your brain tells you to wait.
  3. Ignore temptation: You have to choose the SIP investment over a new gadget or a weekend sale.

The reality is that humans aren’t built for consistent discipline, we are built for habits. An automated SIP investment turns a difficult monthly decision into a one-time setup. The bravery is front-loaded. The habit compounds over time.

“Your OTT subscription doesn’t ask for your permission every month. Your SIP investment shouldn’t either.”

Three structural benefits of automating your Systematic Investment Plan

As an AMFI-registered Mutual Fund Distributor, we emphasize three structural advantages that automated SIP investment may offer advantages that manual investing often struggles to replicate consistently.

  1. Rupee cost averaging: You don’t need to “time” the market. When prices are high, your SIP buys fewer units. When prices drop, it automatically buys more. Over time, this can help average purchase costs across market cycles.
  2. Compounding momentum: Wealth is built on uninterrupted time. Automation helps investors stay consistent with long-term compounding by reducing missed contributions due to forgetfulness or temporary hesitation.
  3. Removal of decision fatigue: By automating the “how much” and “when,” you reduce the need for repeated monthly decision-making, leaving more mental space for your career, your family, and the things that actually require your attention.

SEBI Investor Education: India’s securities regulator publishes free investor education resources on SIPs, risk profiling, and long-term goal planning to help you make informed decisions.

Over long periods, this disciplined approach to SIP investment may help investors stay aligned with long-term financial goals. It is important to remember, however, that mutual fund returns are market-linked and not guaranteed. Consistency, not complexity, is where financial discipline begins.

Automation gives you speed but your SIP investment still needs a map

Automation provides the speed, but without a map, you might end up at the wrong destination. This is where professional assistance becomes vital. At Dhanvantri Capital Services Private Limited, we help investors align SIP decisions with their financial goals, time horizon, and risk profile.

AMFI Investor Corner Understanding SIP: Official explainer from the Association of Mutual Funds in India on how SIPs work, rupee cost averaging, and power of compounding.

Start automating your SIP investment today your future self is waiting

If you can trust an algorithm to pick your next favourite show, it can also help bring consistency to long-term investing habits. The market will always be noisy. Life will always be expensive. But an automated SIP investment runs quietly in the background — helping you stay invested while you focus on life.

It’s time to move your financial discipline from a “task” to a “lifestyle.” Stop managing your money like a part-time job and start treating it like a meaningful commitment to your future self.

“If you can automate your entertainment, you can automate your wealth.”

Start your SIP journey with options based on your financial goals, investment horizon, and risk appetite.

Statutory Disclaimer: Mutual Fund investments are subject to market risks. Please read all scheme-related documents carefully before investing.

Data Disclaimer: Data referenced in this article is based on publicly available sources including AMFI and third-party research platforms, and is for informational purposes only. This article is for informational purposes only and should not be construed as investment advice. Investors should evaluate suitability based on their financial goals, risk appetite, and consult a qualified financial professional before making investment decisions.

Note: Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The past performance of the schemes is neither an indicator nor a guarantee of future performance.

Table of Contents

Ready to make your first investment? Get in touch.

Why Chasing the Highest Return Mutual Fund Can Hurt Your Gains

Why Chasing the Highest Return Mutual Fund Can Hurt Long-Term Wealth

Introduction

I’ve seen this so many times that it’s almost predictable, investors chasing the highest return mutual fund, convinced that last year’s top performer will stay on top. It’s a natural instinct. But after working directly with investors over time, I realised that this single line of thinking is behind most of the avoidable wealth mistakes I’ve witnessed.

“Which fund is producing the greatest returns?”

Genuine question. In the past, even I had the same thoughts. But after working directly with investors over time, I realised that many avoidable investing mistakes often begin with this line of thinking.

It’s natural to look at past returns but chasing the highest return mutual fund based on past performance is one of the most predictable ways to undermine long-term wealth creation.

Why investors buy high and sell low in mutual funds

In everyday life, our actions are quite sensible. You don’t rush to buy more when petrol prices rise. You feel happy buying at lower prices when there is a sale. However, in the stock market and mutual fund investing, this logic often reverses. When the market rises, we feel secure and invest more. When it falls, we become afraid and stop SIPs. This behaviour can be counterproductive for long-term investing.

An actual situation many investors recognise: certain categories of mutual funds performed well over a period and naturally attracted more investor attention. But when markets were weak, most people did not want to invest. They invested only after witnessing strong returns, felt uneasy during volatility, and then asked:
“Should I exit, sir?”

This is often less about the market and more about investor behaviour. The pattern rarely changes. We invest in a fund that’s doing well, it slows down the following year, a different fund rises to the top, we switch and we believe we are acting wisely.

In reality, we are chasing past performance, entering late, and interrupting compounding.

How chasing the highest return mutual fund creates a hidden loss

Real data backs this up: AMFI data showed that 53.38 lakh SIP accounts were discontinued or completed in March, while 52.82 lakh new SIP accounts were registered during the same period. The SIP stoppage ratio rose to 100%, up from 76% in February, even as monthly SIP contributions reached a record ₹32,000 crore.

One straightforward but difficult-to-accept truth: investments with higher return potential may also come with higher volatility and uncertainty. Past performance may or may not be sustained in the future.

Most of us only see returns, not the risk attached to them. What often goes unnoticed is the hidden cost of investor behaviour, something often referred to as the “behaviour gap”. This is the difference between the returns produced by a fund and the returns actually obtained by the investor caused by late entry, early exit, or pausing investments during volatility.

Why SIP investors also fall into the return chasing trap

SIP (Systematic Investment Plan) is designed to promote discipline. However, in reality, the pattern often looks like this:

  • Market rising → SIP is started. Confidence is high.
  • Market declining → SIP is paused or stopped. Fear takes over.

This can disrupt rupee cost averaging, one of the core advantages SIPs are designed to provide. Rupee cost averaging works by buying more units when prices are low and fewer when prices are high. Stopping during a fall does the exact opposite of what the strategy intends.

Trying to capture only the highest recent return can come with trade-offs that are often overlooked. In many cases, disciplined investing and consistency may matter more than trying to optimize every market move.

3 questions to ask before chasing a top performing mutual fund

  1. Does this fit my financial objectives?
  2. Can I manage the level of risk involved?
  3. Can I stay invested for the long term?

Because these factors may help investors make more suitable long-term decisions rather than simply chasing the highest recent return.

Why working with an AMFI registered distributor protects your wealth

As a Mutual Fund Distributor, our role is to help investors understand mutual fund products, scheme features, associated risks, and the importance of disciplined investing. Investor decisions should always be made based on individual financial goals, risk appetite, and investment horizon.

The goal is not to chase short-term returns, but to use a structured approach aligned with long-term goals. The attraction of higher returns is natural. However, decisions made purely on recent performance may not always produce positive results. A disciplined, goal-focused approach combined with a long-term viewpoint can be more effective in supporting long-term wealth creation.

Investor behaviour may often matter more than chasing the best recent performer.

Statutory Disclaimer: Mutual Fund investments are subject to market risks. Please read all scheme-related documents carefully before investing.

Data Disclaimer: Data referenced in this article is based on publicly available sources including AMFI and third-party research platforms, and is for informational purposes only. This article is for informational purposes only and should not be construed as investment advice. Investors should evaluate suitability based on their financial goals, risk appetite, and consult a qualified financial professional before making investment decisions.

Note: Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The past performance of the schemes is neither an indicator nor a guarantee of future performance.

Table of Contents

Ready to make your first investment? Get in touch.

The Sandwich Generation Trap: Why Indian Millennials Are Getting Two Sets of Investment Ideas And Missing a Third Conversation Entirely

The Sandwich Generation Trap: Why Indian Millennials Are Getting Two Sets of Investment Ideas And Missing a Third Conversation Entirely

Introduction

For Indian millennials, the FD vs mutual funds debate isn’t just financial – it’s personal. It’s the first week of the month. Your salary lands. Before you’ve made a single decision, the advice starts flooding in from two very different directions.

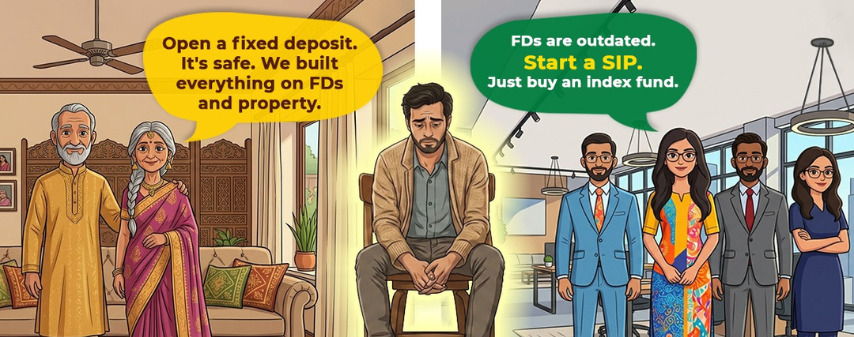
Your parents say: “Fixed Deposit. Property. Gold. It’s safe. We built everything on this.” Your Instagram feed says: “FDs are outdated. Open a SIP. Buy the Nifty 50 index fund and forget it.”

You nod to both. The money sits in your savings account. Weeks pass. This hesitation — this paralysis between two eras of financial thinking is the invisible tax on your wealth.

This is what we call the Sandwich Generation problem. Indians are uniquely caught between their parents’ proven-but-dated financial playbook and a new-wave narrative that dismisses everything their parents built. Both sides have a point. Both sides are missing something.

This article doesn’t pick a side. It builds the case for a third, more important conversation grounded in what the data says in 2026, not what worked in 1995 or went viral last month.

Fixed Deposits for Indian Millennials: Safe, But Are the Returns Enough?

Let’s start with Fixed Deposits. Your parents were not wrong to trust them. India’s banking FD system is DICGC-insured up to ₹5 lakh per depositor per bank, backed by a subsidiary of the RBI. The returns are predictable. For deposits within DICGC insurance limits, the risk of permanent capital loss is relatively low, though access and liquidity may still depend on resolution timelines.

So the question was never really about safety. It was always about whether safety alone is sufficient over a 10–20 year wealth-building horizon. And that’s where the numbers deserve a closer look.

FD Interest Rates India: What Are They Actually Paying in 2026?

As of April 2026, FD rates across major banks sit between 5–7% (Source: Mint). At the same time, India’s average CPI inflation over the last decade has hovered around 5%, according to MOSPI data  meaning an average household has had to spend roughly 5% more on goods and services every single year, year after year.

When you place those two numbers side by side, the picture becomes clear. FDs are traditionally considered safer instruments, but they may not always generate returns that significantly outpace inflation. That distinction matters enormously when you’re trying to build wealth, not just preserve it.

Property Investment India: Why the Math Has Changed for Millennials

Property built genuine, generational wealth for Indian families. Your parents likely bought a home in the late 1980s or 1990s at prices that today seem remarkably low. But the conditions that made possible low entry prices, rising middle-class incomes, limited supply competition are structurally different today, and the numbers reflect that shift clearly.

What Has Actually Happened to Prices?

In Delhi-NCR, residential prices have risen over 81% in just five years, far outpacing salary growth that averaged 8–10% annually over the same period (Source: Week). To put that in practical terms: a home that cost ₹50 lakh in Noida in 2020 costs approximately ₹90–95 lakh today. The salary that was meant to fund that purchase has grown by perhaps 40–50% over the same period.

For many middle-income households in earlier decades, home ownership was often achievable at materially lower income multiples than it is today.

Applying old rules to new prices is where the trap begins. This doesn’t mean property is a poor long-term asset. It means it requires significantly more capital, longer timelines, and more careful planning than it did for the previous generation and deserves honest analysis rather than assumption.

Mutual Funds via SIP: Real Data on What Indian Millennials Are Actually Doing

Something significant has happened in Indian financial markets over the last five years that makes this conversation more urgent than ever. According to AMFI’s official March 2026 data, the mutual fund industry’s AUM now stands at ₹73.73 lakh crore, with 9.72 crore active SIP contributing accounts. Monthly SIP contributions reached ₹32,087 crore in March 2026, and equity schemes have recorded 61 consecutive months of net positive inflows since March 2021.

These are not abstract numbers. They represent millions of Indian households, many of them first-generation equity investors choosing to stay invested through market ups and downs, month after month. Systematic investing through SIPs creates the discipline of contributing through market cycles, which over long periods has historically helped investors participate in equity market growth. For someone with a 15–25 year investment horizon, equity mutual funds deserve a meaningful role in their portfolio.

But the internet has a tendency to simplify nuanced ideas into easy slogans. “Just buy the Nifty 50 index fund and forget it” is one of them. That framing creates confusion rather than simplifying things. Investing works very differently depending on where an approach holds up and where it breaks down. That’s the difference between a strategy and a prescription.

Active vs. Passive Funds: A Decision Based on Context, Not Conviction

As the financial market is dependent on many factors, giving any general statement does not hold any merit on it. There have been periods where certain actively managed funds have shown relative resilience compared to benchmarks. However, this varies across market cycles and fund categories.

There have been market phases where certain actively managed small-cap strategies have shown different downside and return outcomes relative to their benchmarks. However, these outcomes have not been uniform across market cycles, fund categories, or time periods, and are influenced by fund selection, costs, and portfolio construction (Source: ValueResearch).

Why? A Nifty 50 stock has 25–30 analysts on it. A quality small-cap company might have two. That information gap is one reason active management is often evaluated in less efficiently tracked market segments, though outcomes remain dependent on market conditions, costs, and portfolio execution.

The active-vs-passive question does not have a single universal answer. The right approach depends on the asset class, market maturity, investment horizon, and cost structure of available options. A blanket rule applied across a heterogeneous market leads to gaps in portfolio construction.

The Third Conversation No One Is Having

Here is where both the FD generation and the Instagram-investing generation fall short. The real question is not “which instrument is best?” The real question is: best for what?

Every financial goal carries a different time horizon, a different risk profile, and a different ideal instrument. Treating all your investments as a single bucket or choosing instruments based on what feels safe or what performed well recently is how people end up with money that isn’t aligned with their actual needs.

The greatest risk isn’t the market. It’s the lack of alignment.

The real mistake isn’t a lack of intent, it’s a lack of alignment. Not knowing which asset class is appropriate for which goal means that even well-intentioned investors can find themselves unable to grow their wealth toward the milestones that matter most to them. We often treat investments like a single bucket when they should be a toolkit, with each tool matched to a specific job.

In parts of India’s mid- and small-cap market, where information coverage and market efficiency can vary, active management may be considered as one approach depending on portfolio objectives and risk tolerance. In other parts of the market, low-cost passive exposure may serve better. Neither answer fits every situation.

Your parents built wealth through consistency using the tools and knowledge that were available to them and that they genuinely understood. The tools look different today. The discipline is the same. Rather than getting stuck in the Sandwich Generation Trap pulled in opposite directions by two incomplete narratives, the goal is a clear resolve to invest according to your individual risk profile, your financial goals, and your investment horizon.

Clarity is the first step toward better financial decision-making.

In situations like these, the role of an AMFI-registered Mutual Fund Distributor can be to support investors with more structured financial decision-making. We begin by understanding our clients’ goals and future objectives to gain a clear picture of their current investment position and the financial milestones they aim to achieve. Based on each client’s risk profile, financial goals, and investment horizon, we create client-specific investment strategies. Through in-depth research and analysis of both the market and mutual fund performance, we aim to align investment decisions with long-term financial goals.

Data Disclaimer: Data referenced in this article is based on publicly available sources including AMFI and third-party research platforms, and is for informational purposes only. This article does not constitute investment advice. Please consult a qualified financial advisor before making investment decisions.

Note: Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The past performance of the schemes is neither an indicator nor a guarantee of future performance.

Table of Contents

Ready to make your first investment? Get in touch.

Akshaya Tritiya 2026: Honour Tradition, Build Wealth

Akshaya Tritiya Investment Strategy Hero Image

Introduction

For generations, Akshaya Tritiya has been the auspicious day to bring home gold. The word Akshaya means “never diminishing,” and tradition suggests that gold bought on this day ensures eternal prosperity.

But in 2026, a hard financial reality is setting in: The entry barrier for gold has become a mountain.

While the sentiment is beautiful, the price tag is staggering. If your goal is true wealth creation rather than just following a ritual, it’s time to pivot. This year, consider trading the jeweler’s showroom for a meaningful SIP (Systematic Investment Plan) journey.

The Akshaya Tritiya Gold Price Trap

The biggest hurdle today isn’t a lack of faith; it’s the sheer cost of entry. Over the last decade, gold has transitioned from an accessible savings tool to a high-ticket luxury.

Look at how the “entry price” for Akshaya Tritiya has surged. You aren’t just buying gold; you’re buying into a massive price rally.

10 Years of Gold Prices on Akshaya Tritiya (Per 10g)

* Historical gold price data sourced from https://www.ibjarates.com https://www.mcxindia.com

Notice the pattern: The festival day price is almost always higher than the day before. Demand-driven buying pushes prices up exactly when everyone wants to buy. In 2016, you could begin your tradition with ₹30,000. Today, you need close to ₹1,00,000 for that same 10g coin.

Akshaya Tritiya Gold vs SIP: What Actually Grows Your Money?

Is buying gold once a year truly the best strategy for your future? Let’s compare a disciplined SIP with the traditional approach.

Lump Sum Gold vs Rupee Cost Averaging

When you buy gold once a year, you are at the mercy of that day’s market price. If gold is at an all-time high (like it is now), you’ve locked in a high purchase price.

An SIP, however, buys more units when the market is low and fewer when it’s high, averaging your costs and removing the “timing risk.” Read more about rupee cost averaging in detail 

When you buy gold once a year, you are entirely at the mercy of that day’s market price. If gold is at an all-time high (as it is now), you’ve locked in the highest possible cost. An SIP, however, buys more units when the market is low and fewer when it’s high — automatically averaging your costs and removing “timing risk.” Learn more about rupee cost averaging from AMFI India.

Why SIPs Compound, Gold Doesn't

Gold is a “dead asset” in terms of cash flow. It doesn’t pay dividends or grow by itself — it only appreciates if the market says so. Equity SIPs, on the other hand, benefit from the power of compounding, where your returns themselves start generating returns over time. Want to know how it works before you start? Read how SIPs work for you in your wealth creation journey.

At Dhanvantree, we help investors start their SIP journey with a structured, goal-based approach tailored to their financial situation. Talk with Dhanvantree today. 

Akshaya Tritiya Gold vs SIP: The 10-Year Numbers

If you had started a monthly SIP of ₹5,000 back in 2016 instead of making a single gold purchase each year, here is what the numbers look like:

  • Total Investment: ₹6,00,000
  • Estimated Value (at 12% CAGR): ₹11–12 Lakh
  • Gold Appreciation: While gold has grown significantly (from ₹30k to ₹98k), the SIP captures market corrections and growth in a way that a once-a-year purchase simply cannot match.

If you’re unsure how much to invest or which fund category suits your goals, take our risk profile assessmentto get started.

The Psychology Trap: "I Missed the Bus."

Many people look at gold prices in 2016 and sigh, “I should have started then.” But here is the truth: the best time to start was ten years ago. The second-best time is today.

Market volatility in 2026 isn’t a reason to wait — it’s a reason to start an SIP. Volatility is actually an SIP’s best friend, because it allows you to accumulate more units at lower prices over time.

“Don’t wait to invest. Invest and then wait.”

The Ritual Upgrade: Physical Gold vs. Gold ETF

If you feel the need to honour the tradition with a purchase, don’t head to the jewellery store. Even for a small “token” gesture, buying physical gold is the most expensive way to own it.

Instead, consider Gold ETFs (Exchange Traded Funds). You can buy a single unit, representing as little as 1 gram, through your Demat account instantly. It fulfils the ritual of “buying gold” without the massive hidden costs.

Physical Gold vs. Gold ETF: The Real Difference

This year, even if it’s just for shagun, buy a small token of Gold ETF. It’s auspicious, instant, and far more cost-effective than walking into a showroom.

The Akshaya Tritiya Resolution: > “I will invest in my future, not just in a tradition.”

Conclusion Your Akshaya Tritiya Resolution This Year

Start your “Akshaya” wealth journey today

  • This Akshaya Tritiya, don’t just follow tradition — upgrade it.
  • Do a small Gold ETF purchase for Shagun
  • Start a SIP for long-term wealth creation

Get a personalized plan from Dhanvantree. Contact Now.

Note: Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The past performance of the schemes is neither an indicator nor a guarantee of future performance.

Table of Contents

Ready to make your first investment? Get in touch.

Level Up Your SIP: The "Repo-Rate Tilt" Strategy

the hero image of Level Up Your SIP: The "Repo-Rate Tilt" Strategy​ blog

Introduction

Most investors run their SIPs (Systematic Investment Plans) in a straight line. A fixed amount goes into equity, a fixed amount goes into debt, and the pattern rarely changes.

This “set it and forget it” approach is great for avoiding stress, but if you are an advanced investor looking for a way to subtly beat the market, there is a smarter way. By using the RBI’s Repo Rate as a signal, you can “tilt” your investments to follow the heartbeat of the economy.

What is the Repo Rate? (The Simple Version)

The repo rate is the interest rate at which the Reserve Bank of India (RBI) lends money to commercial banks. Think of it as the “master switch” for the economy:

  • When the economy slows down: The RBI cuts the rate. Borrowing becomes cheaper, companies spend more, and the stock market (Equity) usually gets a boost.

  • When inflation gets too high: The RBI raises the rate. Borrowing becomes expensive to cool things down. This usually makes fixed-income investments (Debt) more attractive as interest rates rise.

The Strategy: The "5% Tilt" Rule

Instead of a rigid 50-50 split between Equity and Debt, you let the RBI’s decisions nudge your next month’s investment.

How to execute it:

Start with a base of 50% Equity and 50% Debt. When the RBI announces a change, you adjust only your future monthly SIPs:

  1. The “Growth” Tilt: If the RBI cuts the repo rate, increase your Equity SIP by 5% and reduce Debt by 5%. (Example: Move to 55% Equity / 45% Debt).

  2. The “Safety” Tilt: If the RBI raises the repo rate, increase your Debt SIP by 5% and reduce Equity by 5%. (Example: Move to 45% Equity / 55% Debt).

  3. The “Status Quo”: If the RBI makes no change, keep your SIP weights exactly where they were last month.

The Logic: You aren’t trying to “predict” the market. You are simply following a mechanical rule based on the actual cost of money in the country.

Does it Work? The 10-Year Test

We compared four different ways of investing ₹10,000 every month from January 2015 to November 2025. Here is how much money you would have ended up with:

  • 100% Debt: This is the safest approach, but it offers the slowest growth. Your final wealth would be approximately ₹19.5 Lakh.

  • Static 50-50: In this model, you never change the split between equity and debt. Your final wealth would be approximately ₹25.2 Lakh.

  • Dynamic Repo-Tilt: This strategy adjusts your investment by 5% based on RBI rate changes. Your final wealth would be approximately ₹27.7 Lakh.

  • 100% Equity: This provides the highest growth but comes with the highest stress and volatility. Your final wealth would be approximately ₹30.9 Lakh.


A Note of Caution for Smart Investors

While this strategy is effective, it requires a “Level Up” in your management:

  • Don’t Churn Old Money: This rule should only apply to your new monthly SIPs. If you try to move your entire accumulated balance every time the RBI speaks, you will lose a lot of money to taxes and exit loads.

  • Patience is Key: The economy doesn’t react to rate changes overnight. This is a long-term play that proves its worth over 5 to 10 years, not 5 to 10 months.

  • No Blind Following: This is a sophisticated tool for those who enjoy tracking macro-economic signals. If you prefer a completely “hands-off” life, the standard SIP is still your best friend.


Note: Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The past performance of the schemes is neither an indicator nor a guarantee of future performance.

Table of Contents

Ready to make your first investment? Get in touch.

The Illusion of Safety: Why Debt Risk is Scarier Than Equity Risk

the hero image of The Illusion of Safety Why Debt Risk is Scarier Than Equity Risk blog

Introduction

We’ve been conditioned to believe a simple financial binary: Equity is a roller coaster; Debt is a steady climb.

When you invest in an equity fund, you prepare for battle. You know the market will swing, and you expect the Red Days. But when you invest in a debt fund, you’re looking for peace of mind. You expect a smooth, boring, upward-sloping line.

The reality? That “boring” line can be far more dangerous than the volatile one. In equity, risk is loud. In debt, risk is silent.

Equity Risk: The Loud, Transparent Enemy

Equity risk is honest. It doesn’t hide. When a global pandemic hits or interest rates rise, the stock market screams. You see the NAV (Net Asset Value) drop by 2%, 5%, or even 10% in a week.

Because equity risk is so visible, it forces you to build a temperament. You learn to live with the fluctuations. You understand that the price you pay for long-term wealth is enduring short-term chaos. In equity, the “pain” is distributed over time in small, frequent doses.

Debt Risk: The Silent Assassin

Debt funds are designed to look safe. Most of the time, the NAV moves up in tiny, consistent increments. It looks like a staircase to heaven—until it isn’t.

While equity risk is about Volatility, debt risk is primarily about Credit and Liquidity.

The “Steady Line” Trap

When a debt fund manager chases higher returns (yield), they often buy bonds from companies with lower credit ratings. On a daily basis, these bonds pay interest, and the fund’s NAV continues its steady climb. Everything looks perfect.

The “Credit Event”

The risk in debt funds doesn’t manifest as a slow decline. It manifests as a cliff.

If a company whose bonds the fund holds suddenly defaults or gets downgraded, the fund must “write down” the value of that paper instantly. You won’t see a series of small red days. Instead, you wake up to find the fund has dropped 5% or 10% overnight.


Why Debt Losses Hurt More

Losses in debt funds don’t knock politely; they break down the door. Here is why they are psychologically and financially harder to handle:

  1. The Recovery Time: If an equity fund drops 10%, a good bull market can recover that in a month. If a debt fund yielding 7% drops 7% due to a default, it takes one full year just to get back to zero. You haven’t just lost money; you’ve lost time.

  2. The False Sense of Security: You don’t hedge for debt risk the way you do for equity. You might put your emergency corpus or “safe money” there. When the “silent” risk speaks up, it usually happens when you can least afford it.

  3. Liquidity Freezes: In extreme credit events, debt funds may even “gate” withdrawals, meaning you can’t get your money out even if you’re willing to take the loss.

How to Protect Yourself

Does this mean you should avoid debt funds? No. It means you must stop treating them like “high-interest savings accounts.”

  • Check the Portfolio: Look at the credit quality. If a fund is offering 2% more than its peers, it isn’t “better managed”—it’s taking more risk.

  • Prioritize Safety over Yield: Use debt funds for stability. If you want 12-15% returns, go to Equity. Don’t try to squeeze equity-like returns out of a debt instrument.

  • Stick to High Ratings: For your core “safe” bucket, look for funds that invest in Sovereign (Government) bonds or AAA-rated corporate bonds.

Conclusion

In the world of investing, transparency is your best friend.

Equity risk is like a stormy sea: the waves are high and the boat rocks constantly, but you wear a life jacket because you can see the danger. Debt risk is a sinkhole: the ground feels solid and the path looks clear, right up until the moment it disappears beneath your feet.

The “safety” of debt is often an illusion created by a lack of daily drama. Real security comes from recognizing that:

  • Volatility (Equity) is a temporary dip you can recover from.

  • Default (Debt) is a permanent loss of capital that can take years to recoup.

Don’t let a smooth line fool you. If a debt fund’s returns look too good to be true, the risk isn’t absent—it’s just waiting. Prioritize transparency over “quiet” gains, and ensure your safe money stays truly safe.

Note: Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The past performance of the schemes is neither an indicator nor a guarantee of future performance.

Table of Contents

Ready to make your first investment? Get in touch.

Liquidity Trap: How Cash Hoarding Erodes Your Returns

the hero image of Liquidity Trap How Cash Hoarding Erodes Your Returns blog by dhanvantree

Introduction

In India, millions of households continue to hold onto cash, even as markets deliver impressive returns. The preference for safety over growth may feel comforting, but in reality, this behavior mirrors a liquidity trap—a situation where excess savings and fear of investment slow both individual wealth creation and the broader economy.

While the term has its roots in Western macroeconomic theory, its implications for Indian savers and investors are highly relevant today. Let’s break down how cash hoarding works against you, and what you can do to break free.

What is the Liquidity Trap?

The liquidity trap was popularized by economist John Maynard Keynes, who explained how monetary policy can lose effectiveness when people prefer to hold cash instead of spending or investing. At its core, the liquidity trap describes a situation in which central banks lower interest rates close to zero, yet people still hoard money instead of investing. In theory, cheap credit should encourage borrowing and spending. In practice, it often leads to cash hoarding, especially when uncertainty clouds the future.

  • Typical Signs: Low interest rates, sluggish demand, and a tendency to hoard money.

  • Why It Matters in India: Even though India’s repo rate isn’t near zero, the psychology of risk-aversion among savers creates a trap-like environment. Despite rising markets and opportunities, households often keep money idle in bank accounts or under mattresses.

Why Indians Prefer Holding Cash

Indian investors’ cash preference has deep cultural, economic, and behavioral roots:

  • Fear of volatility: Market corrections often trigger panic, leading people to exit equities and hold cash.

  • FD loyalty: Fixed deposits and savings accounts are trusted, but returns rarely beat inflation.

  • Cultural bias toward safety: Gold, cash, and FDs dominate family financial planning.

  • Waiting game: Many investors hold cash “for the right time” but miss opportunities when markets recover faster than expected.

Economic Implications of Holding Excess Cash

Holding cash feels safe, but it comes with hidden costs:

  • Inflation erosion: ₹10 lakh sitting in savings loses purchasing power every year. At 6% inflation, real value shrinks quickly.

  • Lost compounding: Money left idle misses out on the exponential growth of equities or even debt funds.

  • Opportunity cost: Indian equities have historically delivered strong long-term returns—cash holders miss rallies.

Example: ₹10 lakh kept as cash for 10 years loses ~45% of its real value (due to inflation). The same amount invested in a Nifty 50 SIP could potentially increase or more, depending on market cycles.

Case Studies and Real-World Examples

  1. The Great Depression and Liquidity Preference: In the 1930s, fear paralyzed economies. Even with near-zero rates, people refused to spend, worsening deflationary pressures.
  2. Japan’s Lost Decade: Japan’s economy stagnated in the 1990s as consumers and businesses held onto cash despite government efforts to stimulate growth.
  3. Modern Central Bank Policies: Quantitative easing (QE) in the U.S. and Europe attempted to push cash into the economy. Yet, much of it ended up in savings or reserves, showing how stubborn liquidity traps can be.

What Investors Can Do to Escape the Liquidity Trap

  • Keep only emergency cash: Maintain 3–6 months of expenses in savings for emergencies, not investment capital.

  • Use liquid funds for idle money: Park surplus cash in liquid or ultra-short-term funds to earn better returns than savings accounts.

  • Start a SIP (Systematic Investment Plan): Invest regularly in equity or hybrid funds to benefit from rupee cost averaging and long-term compounding.

  • Diversify investments: Spread money across equities, debt instruments, and gold to balance safety and growth.

  • Deploy cash strategically: Use market corrections and RBI policy cues as opportunities to invest instead of hoarding.

  • Focus on inflation-beating returns: Choose instruments that consistently deliver above inflation, ensuring real wealth growth.

Broader Economic Implications

  1. Weak Consumption Demand: India’s growth engine relies heavily on consumer spending, which accounts for nearly 60% of GDP. When individuals hoard cash, they cut back on discretionary spending—whether it’s buying a new vehicle, upgrading housing, or increasing retail purchases. This weak demand slows down industries such as real estate, automobiles, and consumer goods, which in turn drags on employment and income growth.
  2. Lower Capital Formation: Companies depend on both consumer demand and investor confidence to fund expansion. Cash hoarding by households and institutions limits the flow of money into financial markets and banking systems, reducing the pool of available capital. This leads to slower infrastructure development, weaker private investments, and reduced innovation, making it harder for the economy to create sustainable growth momentum.
  3. Impact on GDP Growth: Weak demand discourages businesses from expanding, which lowers job creation and wage growth, leading to even more cautious saving behavior. This cycle ultimately drags down GDP growth, keeping the economy below its potential trajectory. In a developing country like India—where rapid growth is essential for poverty reduction and wealth creation—the effects are especially damaging.
  4. Monetary Policy Ineffectiveness: When individuals and businesses refuse to spend or invest, RBI’s liquidity injections and interest rate cuts lose their effectiveness. Even with cheap money available, if confidence is low, banks hesitate to lend and consumers avoid borrowing. This diminishes the power of traditional monetary policy tools, leaving the government with fewer options to stimulate growth.
  5. Inflation Paradox: While cash hoarding reduces demand and can suppress inflation in the short term, it can also create instability in the long term. When spending eventually resumes in bursts, it can fuel demand-pull inflation, catching policymakers and investors off guard. This volatility makes long-term economic planning difficult.

Conclusion

Hoarding cash may feel safe, but in reality, it erodes wealth and stalls growth. Inflation eats into savings, while missed investment opportunities weaken financial progress. For Indian investors, the smarter path is clear: keep only emergency funds in cash, and let the rest work through SIPs, liquid funds, and diversified investments. In the long run, money grows only when it moves.

Dhanvantree, an AMFI-registered mutual fund distributor, can assist you in building the right investment strategy to break free from the liquidity trap.

Note: Mutual fund investments are subject to market risks. Please read all scheme-related documents carefully before investing. The past performance of the schemes is neither an indicator nor a guarantee of future performance.

Table of Contents

Ready to make your first investment? Get in touch.